Showing posts with label ponzi. Show all posts

Saturday, 11 July 2020

The Voice - Consumer's Voice

Must I pay them?

I bought a laptop at some shop at Game City the past Sunday. When I get home I installed programs inside and I noticed it doesn’t have a CD drive, of which I wanted the one with CD drive. Then on Monday I called the shop to explain so that I could return the laptop, they asked me to come to the shop.

I only installed the word and excel on the laptop, I sent my sister to return the laptop since I stay far, but they didn’t refund her but she left the laptop with them. They said they want me to come. They said they will refund me and charge me P500 because I installed office word on it.

So what I am asking is can I get a refund from the shop because they say they don’t have a laptop in store that have a CD drive? And is it even allowed for them to charge me that much?


These days you’ll see that many laptops don’t have CD or DVD drives, particularly the smaller, more portable ones. In 2020 software is often installed by downloading installers from software company web sites, not the old-fashioned way by using an installation DVD.

I think this all depends on how the store described the laptop when you bought it. Did they say it had a CD drive? Did any advertisement or product packaging say it had a CD drive? Did you tell them that’s what you wanted?

However, I don’t understand this story about wanting to charge you P500 for installing your software. Firstly, that should have been something you did before you returned it and secondly, it shouldn’t take them much effort to uninstall the software. If you send me details of the store I’ll get in touch with them and see if they can be a bit more adaptable.


How can I spot a scam?

There are several pyramid and Ponzi schemes active right now and they’re doing their best to recruit people by promising them vast profits.
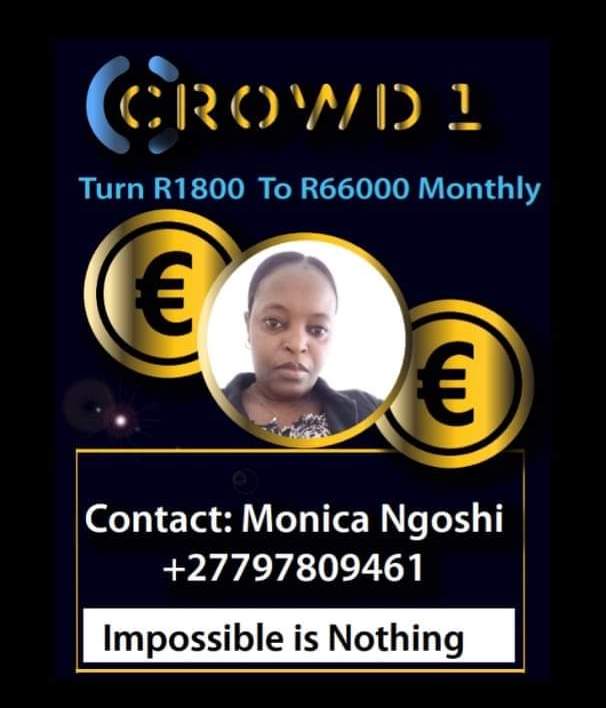

Crowd1 is still very active, despite either being declared illegal or consumers being warned to avoid it in various countries around the world.


Right now, people are also desperately trying to recruit people into a “WhatsApp gifting” scam that promises to multiply the money people pay to join. Both are nothing more than scams that rely on gullible victims joining and then recruiting multiple levels of other victims beneath them. Several readers contacted me asking me to repeat the clues I gave a few weeks ago about how to spot these scams.


Whenever someone invites you to join their money-making scheme, ask yourself WHY they’re inviting you. If they’ve found a way of making money, why are they sharing it with you instead of keeping it to themselves? The answer is very simple. Anyone inviting you to join their scheme is trying to make money FROM you, not WITH you.

Another clue is products. Real businesses have products and services. Scams don’t. Or if they do, or they only pretend to have them, but they don’t really matter. They are primarily interested in recruiting other people and then getting them to recruit even more. You’ll often hear the promoters of these schemes defend themselves by insisting their scheme isn’t a pyramid scheme because there are products. Others will say it’s legitimate because anyone can earn more than the people above them in the pyramid. That’s all just excuses. What matters most is the word “primarily”. Section 9 of the Consumer Protection Act says that if “participants in the scheme receive compensation derived primarily from their respective recruitment of other persons as participants” then it’s a pyramid scheme. It’s not difficult.

There are also some key words you should look for. One is Bitcoin. As I’ve said in the past, Bitcoin is a legitimate but very high-risk cryptocurrency that is a fascinating vision of how money might work in the future. However, it must never be seen as an investment and it’s surrounded by a huge number of scams, pyramid schemes and Ponzi schemes. A good example was BitClub Network, whose founders are being prosecuted in the USA for running a scam that stole $722 million from victims around the world. That actually had no connection to Bitcoin at all, it was just an enormous Ponzi scheme and there were plenty of victims in Botswana.

The simplest lesson is to be skeptical. Don’t believe anyone who claims you can make large amounts of money with little effort or just by recruiting other people. Anyone who claims this is either lying, deluded, naïve or desperate. Don’t believe it!

Saturday, 27 June 2020

The Voice - Consumer's Voice

Can I get a better bed?

Hi. In 2017 November I bought a bed and a fridge in Bradlows Game City branch in Gaborone which was delivered to my home by Mahalapye branch.

In 2018 I reported the bed because it had a depression in the middle and was sagging in less than 6 months. I was given an exchange and given a new bed of the same brand which did the same thing again and I lodged a complaint which took some months without being assisted. In 2019 October was given a new bed which is a lower quality from the previous one and its worse. In less than 2 years I had used 3 beds which I did not find any value for my money.

I have raised an issue with the managers to no avail. I am being tossed from pillar to post and their call center is harassing me and tormenting me on daily basis. They are telling me the bed is off guarantee therefore they cannot help me.


This is going to be complicated. I suspect the store will continue to argue that they provided you with a bed throughout the period you were paying for it and for much longer than the period of the warranty they offered. That’s one of the most frustrating things about buying things on hire purchase, the payment period is usually two years but the warranty is almost always only one year. If the product goes wrong after the first year you’re left paying for something that doesn’t work properly and there’s nothing you can do about it.

I know it doesn’t seem this way but you were lucky that the store gave you a new bed, even a poorer quality one, nearly two years after the purchase. I don’t think they were actually required to do that if the warranty was only for a year.

Nevertheless, I’ve contacted Bradlows to see if there’s anything they can do but please, don’t be too optimistic.

How can I spot a scam?

Given how many people are falling victim to a variety of scams, several readers have asked how they can spot a scam before they fall victim to it. So here are some ideas.

Whenever someone invites you to join their money-making scheme, you should first ask yourself WHY they’re inviting you. If they have a way of making money, why are they sharing it instead of keeping it to themselves? The answer is very simple. Anyone inviting you to join their scheme is trying to make money FROM you, not WITH you.

Another clue is products. Real businesses have products and services. Scams don’t. Or sometimes they do, or they pretend to have them, but these products don’t really matter. They are primarily interested in recruiting other people and then getting them to recruit even more. You’ll often hear the promoters of these schemes defend themselves by insisting their scheme isn’t a pyramid scheme because there are products. Others will say it’s legitimate because anyone can earn more than the people above them in the pyramid. That’s all just excuses. What matters most is the word “primarily”. Section 9 of the new Consumer Protection Act says that if “participants in the scheme receive compensation derived primarily from their respective recruitment of other persons as participants” then it’s a pyramid scheme. I think that’s quite simple.

There are also some key words you should look for. One is Bitcoin. As I’ve said endless times in the past, Bitcoin is a legitimate but very high-risk cryptocurrency that is a fascinating vision of how money might work in the future. However, it must never be seen as an investment and it’s surrounded by a huge number of scams, pyramid schemes and Ponzi schemes. Just like the BitClub Network, whose founders are being prosecuted in the USA for running a scam that stole $722 million from victims around the world. That actually had no connection to Bitcoin at all, it was just an enormous Ponzi scheme.

The simplest lesson is to be skeptical. Don’t believe anyone, not a single soul, who claims you can make large amounts of money with little effort or just by recruiting other people. Anyone who claims this is either lying, deluded, naïve or desperate. Don’t believe it!

Sunday, 21 June 2020

The Voice - Consumer's Voice

Must I pay them?

Hello sir I need your assistance. In 2010 I applied for a loan amounting to 36,000. Then in 2012 before finishing the loan I got a sponsorship to further my studies, I went for 5 years to study. During that time the loan wasn't been serviced or not paid monthly. So when I came back I went to them to check with my credit so that I repay them but I found it at P80,000. I tried to negotiate so I pay where from where I left of which was around P45,000 balance they said is not possible. Please help me on what to do.


Unfortunately, I’m not sure there’s much I can do to assist. This is what happens when you default on a loan. The lender will continue to add interest and penalty charges to the amount you owe them. When they engage debt collectors their costs will also be added to the bill. Then if they instruct attorneys to take legal action against you those costs will also be added to the amount you owe. If you go back and read your loan agreement carefully you’ll see that you agreed to all of this when you first applied for the loan.

I’m not trying to be unhelpful but look at it from the lenders point of view. Imagine if you’d lent someone a lot of money and after paying it back for a short time they disappeared for five years without honouring the debt. Wouldn’t you be angry? Wouldn’t you engage a debt collector and then attorneys? Wouldn’t you want to charge them extra for the bother and costs you’d incurred?

The lesson for all of us is whenever you owe someone money and then you have financial difficulties or your circumstances change, the lender must be the first person you call. Give them some warning that there will be problems and it’s much more likely that they’ll be flexible. Big lenders might offer you a repayment ‘holiday’ to give you time to get your affairs in order. They might also renegotiate the repayment schedule so that is easier for you. Remember that lenders want their money back as easily as possible. They really DON’T want to spend their time and money chasing you. They want an easy life.

I suggest that you contact the lender and ask to meet with them to negotiate a repayment plan that you can afford and that gives them their money as quickly as possible.

What can I do about this Bitcoin scam?

I just read your viewpoint online about Bitcoin and how it is not the most advisable to invest in. I’m actually asking on behalf of a group of 60 victims whom were mainly introduced into buying bitcoins by a certain lady who I would say is the guru in Botswana.

Late last year she informed us that the website where we were mining had “crashed” because of an influx of people. Then she blamed the court case of Bitcoin founders! After a lot of frustrated comments towards her in our Whatsapp group she then muted us. She presented herself as the know all, on top of all things Bitcoin but when asked for answers about the whereabouts of our monies suddenly she’s just as in the dark as everyone else. Her actions and responses are also very defensive, careless and insensitive.

Kindly advise me if we have a valid case in taking this matter forward or should we just count our losses and move on. Your help will be highly appreciated.


Yes, I have been very critical of people suggesting that Bitcoin can be seen as an investment. There’s nothing wrong with Bitcoin itself, it’s a legitimate cryptocurrency. If you want to use it to buy and sell things then that’s acceptable but remember that its value is extremely unpredictable. Remember also that it’s entirely unregulated and there are absolutely no protections if something goes wrong. The Bank of Botswana is not going to help you if there’s a disaster.

However, your situation is more complicated. You never had any connection with Bitcoin, you were dealing with a scam called BitClub Network. They were nothing more than a Ponzi scheme. Like all such scams it eventually collapsed and the one piece of truth you were told by the woman who recruited you is that there really is a court case currently underway. The people behind BitClub Network are currently being prosecuted in the United States for running a Ponzi scheme that led to people like you losing a massive $722 million.

We’ve been warning people about BitClub Network since late 2016 and I’m sorry that the warnings didn’t go far enough. I think the person who recruited you and the other recruiters need to be brought to justice for promoting an illegal scam. Let’s send the information to the authorities and see if they’re prepared to take action!

Monday, 23 December 2019

BitClub Network - $722 million gone missing, prosecutions beginning

A couple of years ago I was on radio and mentioned Bitcoin. I warned people that I thought it was an "economic bubble" and that its rapidly increasing price was very likely to come crashing down soon.

Later that day the station called me saying that "Bitcoin" had asked to come on air to provide another side to the story. I mentioned that there is no company called "Bitcoin" so I didn't see how they could send a spokesperson. They gave me the number of the person who had called and it was actually someone from BitClub Network, an obvious pyramid / Ponzi scheme. They claimed to be major Bitcoin miners but there was NO actual evidence of that being true.

They said:
“With BitClub Network you earn daily profits from our shared mining pools. We also have a referral program so you can get paid for anyone you refer.”
In fact, their main motivation was to recruit more and more people, a major clue that all was not as it seemed.

The people behind this scam are now facing prosecution in the USA but the sad thing is how many people fell for the lies told by BitClub Network recruiters and who collectively lost £722 million.

Please, let's not fall for another BitClub Network, Eurextrade or MMM Global? Let's make that a New Years Resolution for 2020?

Wednesday, 30 October 2019

The Voice - Consumer's Voice

Is Crowd1 a pyramid scheme?

I would like to ask about Crowd1 investment group, how genuine is it? Is it a pyramid scheme?


Yes, it’s possible. The other possibility is that it’s a Ponzi scheme. Either way, it doesn’t matter, getting involved could result in serious fines and even jail time.

Several people have approached us recently asking the same question and it really seems that this South African scam is now looking for victims here in Botswana.

I joined one of their WhatsApp conversations and the introduction was always the same. “I would like to introduce you to a legitimate business that is paying so well and is still new globally. You get paid even if you dont recruit Register and earn real money.” There’s an interesting clue there. Why would a legitimate business make such a point about being legitimate? It’s a bit like a stranger introducing himself by saying “Hi, I’m not a criminal”.

The other clue comes in the next sentence in the conversation. “TURN R1800 TO R66000 MONTHLY SALARY”. I asked whether that was really correct, that by paying just “R1,800, you could earn R66,000 every month and they were clear that this was possible. However, they couldn’t give any real explanation about where the extra money might come from. Curiously, they also claim that people joining can make profit of “100% In 5 Days” and a bonus of “50% Per Referral”.

I think this is most probably a Ponzi scheme, in which some of the money paid by people to join is passed on to people who joined earlier. That’s the referral payment they’re talking about. In fact, what happens in most Ponzi schemes is that money isn’t actually paid to the people joining, it’s just held in a fake account online. The victims are often prevented from withdrawing their money because it doesn’t actually exist.

The good news for Botswana and the bad news for Crowd1 and anyone promoting it or even joining it is that this scheme is illegal. Section 9 of the Consumer Protection Act 2018 outlaws what it calls a “multiplication scheme which “offers, promises or guarantees … an effective interest rate that is above the market rate”. It also outlaws what it calls “chain letter schemes” in which “each successive newly recruited participant is required to make some form of payment which would be distributed to some of the previously existing participants”. The punishment for even joining such a scheme can be a fine of up to P100,000 or five years in prison. Are you prepared to take that risk?

Is the interest correct?

I bought some furniture a few months back on hire purchase. I was doing some end of year computations when I noticed that the interest charged on this contract of P1567.68 is precomputed. This means that it doesn't take into consideration the fact that the principal amount is been reduced with every instalment going forth and it will not change unlike in the AMORTISED system. Is this legal considering that they demand instalments which include capital. This doesn't favour consumers.


Do you think there is anything about hire purchase that favours customers? I don’t.

There are so many things I don’t like about hire purchase. The goods you think you’re buying don’t belong to you until you’ve made the final instalment, they remain the property of the store. The store can repossess the goods if you fall behind with your payments without a court order. The insurance included in the hire purchase agreement is often up to ten times as expensive as the insurance policy you can get elsewhere. If you buy something on hire purchase over two years, the total amount you pay is often double the cash price. Even if the goods are repossessed you can still owe the full amount or more once they add penalties and interest. The warranty on the goods you buy is usually only one year so if it goes wrong on the 366th day, you get no support and you still must pay for another year for something that no longer works.

Your question about interest is a good one but it’s not how hire purchase payments are made. As you say, the interest is calculated at the beginning of the contract and along with the various other elements such as delivery charges, installation and handling fees, contract costs and insurance and the total is then divided by the number of instalments and you pay them evenly throughout the entire period of the agreement.

Wednesday, 1 May 2019

The Voice - Consumer's Voice

Is this a genuine job offer?

I received an email from Al Zawali Construction in the United Arab Emirates saying that my “qualifications and experiences which you submitted online matched the requirements for our on going employment”. I don’t remember submitting my details online so do you think this is genuine?


It’s a genuine scam, that’s for sure.

Here’s a simple truth. Employers don’t contact total strangers offering them jobs. The email you sent me contained a few clues that it wasn’t genuine. Firstly, the email didn’t include your name, it just said “Greetings”. if it was true that they saw your details online, don’t you think they would know your name? Then they ask you to send your CV. Surely, if this was genuine, they’d have seen it already?

Then there’s the language they use. “qualifications and experiences”? “for our on going employment”? Does that sound like a well-educated HR professional to you? It doesn’t to me.

There are other clues that you need some cyber-detective skills to notice. Their web site says that “Over thirty thousand(30,000) employees have worked at the company for over 10 years and nearly half of the 1000+ employees have worked at Al Zawali Contruction Company for more than five years” but their
domain, alzawaliconstruction.com, was only registered on 2nd March 2019. And they can’t spell the name of their own company correctly!

There’s one final clue that you wouldn’t know about. Consumer Watchdog received exactly the same email a few days ago. We certainly didn’t post our profile online because Consumer Watchdog isn’t a person.

This is the beginning of an advance fee scam. Sooner or later they’ll demand money from you in order to obtain the fake job they say they’re offering. They’ll probably say it’s for a visa or legal fee and that’s what this scam is all about, that advance fee. Even if you pay them it won’t stop, they’ll keep demanding money until you either realize it’s a scam or you simply run out of cash. Please don’t waste your time and money.

Is Donations for Wealth real?

You’re not the first to ask us this. You won’t be the last.

Donations For Wealth describe themselves on their web site as "a 21st Century Donation system and Crowd Sharing Platform” and that “Now Here's A Sure Way To Get The JUMP On a Money Train & Start Making More Money Than You Ever Thought Possible!”

They claim that their business “brings forth a new way of raising funds for various causes, whether it is for personal needs or a host of worthy causes, such as Paying off Debts, Groceries, Holiday, Weadding, Buying a car, churches, schools, non-profit organizations, etc."

“Weadding”?

This is the language used by Ponzi schemes. You “donate” money into the scheme and somehow, perhaps magically, greater amounts of money come back to you. For instance they claim that you can “Turn R10 into R100,000“ without explaining how this might be possible. They then claim that recruits can “Turn R100 into R40,000” which is surprising as it’s less than the first offer for a bigger “donation”. Perhaps most impressively they suggest that you can “Turn R5 into 2 Million”.

Like other Ponzi schemes they don’t even attempt to explain how the money they claim you can make is generated. That’s because like with other such scams the only source of new money is from the people who join after you. That’s where they get the small amounts of money they might offer you in return for your “donations”. That’s how a Ponzi scheme works.

Like all Ponzi schemes Donations For Wealth will collapse. Their domain was only registered in February this year so they’ve had a couple of months to steal people’s money. I predict they’ll be gone with victim’s money in another few months. Please don’t be one of those victims!

Also, remember that Section 9 of the Consumer Protection Act outlaws Ponzi schemes as well as pyramid schemes. Do you want to run the risk of a fine of P100,000 or five years in prison even for just joining a scam like this one?

Saturday, 20 April 2019

Consumer Alert - Donations For Wealth

Consumer Alert
Donations for Wealth


Donations For Wealth describe themselves as:
"a 21st Century Donation system and Crowd Sharing Platform. It brings forth a new way of raising funds for various causes, whether it is for personal needs or a host of worthy causes, such as Paying off Debts, Groceries, Holiday, Weadding, Buying a car, churches, schools, non-profit organizations, etc."
They also say that they are the "No 1 World's best donation system" make some remarkable offers:
Turn R5 into 2 Million / Turn $ 0.40 into $150,000
Turn R10 into R100,000 / Turn $1 into $6920
Turn R100 into R40,000 / Turn $7 into $2700
Turn 500 into R135,000 / Turn $34 into $9160
Turn R500 into R20,000 / Turn $34 into $1358
Turn R50 into R5000 / Turn $3.40 into $340
Turn R200 into R4600  / Turn $14 into $312
Turn R500 into R21000  / Turn $34 into $1400
And then they claim that you can "Turn A once-off R10 to over R100,000".


Given that there are no products, that the only source of income seems to come from subsequent recruits, it's clear that Donations for Wealth is a Ponzi scheme. Or maybe a pyramid scheme. One of their Facebook posts was very simple about the business model:
"Lets work hard and Make money! Recruit Recruit Recruit!!"
The FAQ page on their web site (the domain for which was only registered on 12th February this year) includes the question "Can I sign people up myself?" and answers:
"Yes you can. In fact, you are encouraged to do that to make sure that the people you refer are placed under the correct Referrer, which is you."
One of their Facebook posts was very simple about the business model:
"Lets work hard and Make money! Recruit Recruit Recruit!!"
Whether it's a Ponzi scheme or a pyramid scheme doesn't really matter. Either way it's illegal.

Wednesday, 23 January 2019

Radio show notes - week beginning 14th January 2019 - Predictions

Source: Wikipedia
Predictions for 2019

Here are our predictions for 2019. No, we don't have psychic abilities, just enough evidence and intuition to feel certain that they'll come true.

1. People will still sign things they shouldn’t sign, and won’t sign things that they should sign

People will continue not to read and understand hire purchase and loan agreements, tenancies and, most importantly, investments and insurance product policies. They'll carry on assuming (incorrectly) that “verbal” agreements have some value when they later need to take action against someone who has abused them. This failure will be exploited by less-than-honest people.

2. Cellular network operators

We will continue to be disappointed, frustrated and angered by cellular network providers who appear to be short-changing us with airtime, data and general quality of service.

3. Some event organisers will continue to be useless

Is any further explanation necessary?

4. Ponzi and pyramid schemes

Ponzi and pyramid schemes will continue to promise wealth, comfort and excitement in return for recruiting multiple levels of victims beneath us. They will have only one aim: to make lots of money for the people at the top and at the expense of those lower down. However, they’ll soon face the fact that, for the first time in our history as a nation, their schemes are now illegal. Section 9 of 2018 Consumer Protection Act will make a difference.

5. Electricity and water will continue to increase in price

That’s just how life is.

6. Public transport providers

Some public transport providers will continue to be awful, horrible people who hold their paying customers in contempt and will continue to employ psychopaths as drivers.

7. Miracle cures

Peddlers of miracle and magical health claims will find that Botswana is a harder place to sell their dangerous lies. They won’t go away but they will be silenced more quickly thanks to new and more effective regulators.

8. Regulators

Regulators with an interest in consumer protection will be a bit more effective BUT only if consumers demand that they do and support them by raising issues and submitting complaints to them. BOCRA, BOMRA, BOBS, NBFIRA are all being more active. We pay for them to exist, so let’s get our money’s worth.

9. Best Before and expiry dates

Best Before dates will continue to be just advisory. Expiry dates will continue to be the things that matter. Consumers will continue not to understand the difference.

10. My Salary might have competition

There will be even more dedicated, inspirational and amazing people working in customer service.

11. It's 2019 

Some companies will understand that it’s 2019 and the ways they engaged with customers in the past are out-dated. They’ll understand that, whether they like it or not, consumers can now express their feelings wherever, whenever and however they like. And there’s nothing companies can do about that. Their choice will be to accept that and work with it, or die.

12. Bitcoin

People will continue to say that Bitcoin is the future of money but they’re probably related to those who said MySpace was the future of the internet. Something like Bitcoin might end up being important and blockchain technology is fascinating but don’t believe the hype. It’s an area that will continue to have more than its fair share of Ponzi and pyramid schemes and other scams. Victims will lose a lot of money.

13. 2019

In 2019 Consumer Watchdog will spend even more time on consumer education. I mean LOTS more time. Watch this space!

Saturday, 22 December 2018

Radio show notes - week beginning 17th December 2018

Source: Wikipedia
1. “Frontloading”

A consumer invested P42,000 in 2 education policies. He later defaulted on some premiums because he had resigned from his job to start own business. Given his new situation he decided to cancel the policies and attempted to withdraw the money he'd invested so far.

The surprise was how much was returned to him.

P1,440.

He was told that the reason was “the money was used for admin.”

He commented:
“Morally that is wrong. One would expect they should pay me some interest for the money I invested with them.”
This was an example of “front-loading”. Long-term investment products, such as education policies are meant to last for many years, maybe 10 or 20 years. But the agents and brokers selling these products don't want to wait that long to get their commission. If you read the small print you'll see that the admin expenses and commissions are often taken in the first year or two of the policy. It's only after a few years that your money starts to grow.

BUT, do consumers understand this? Did the agent or broker that sold them the policy explain this? Did the insurance company do enough to ensure that their customers understand?

2. Insurance vs investments

There is a lot of confusion about investments and insurance policies.

Investments and savings schemes are about putting money somewhere safe. With luck you might even earn some interest on the money you contribute but remember "front-loading".

Insurance is about transferring risk, or at least the financial cost of risk. Whether it's your vehicle, your house or its contents, your health or your life, an insurance policy will cover the cost of something bad happening.

3. CBN - a pyramid scheme
[A number of people asked us to repeat this warning, so here goes.]

(See also our press release about CBN here.)

“P100 can change your financial situation. CBN is a way to go. Join me today and let me take you through the journey of that financial change. You won't regret taking that decision. Drop your number now. Remember your P100 is a once off.”
Apparently you can join for just R100 and recruit 6 people, “You earn R10 per downline” and then get P60. And then so on, through several levels:
  • Level 1 Worker
  • Level 2 Supervisor
  • Level 3 Manager
  • Level 4 General Manager (at which you apparently get a laptop worth R4,000, groceries R2,000 and a Marketing allowance of R500.)
  • Level 5 Assistant Director (at which you get a Sun City holiday)
  • Level 6 Director (now you get a car worth R200,000)
  • Level 7 Acting CEO (another car, this time worth R500k)
  • Level 8 CEO (yet another car, now worth R1,200,000, a house valued at R2,500,000 along with furniture worth R500,000). 


CBN claim that:


“It’s simple to work with us: Recruitment only, no selling products, no products maintaining.”
Section 9 of the 2018 Consumer Protection Act defines a pyramid scheme as a scheme:
“where participants in the scheme receive compensation derived primarily from their respective recruitment of other persons as participants”
It goes on to warn that:
“A person shall not directly or indirectly promote, or knowingly join, enter or participate, or cause any other person to promote, join, enter or participate in… A pyramid scheme”
and that:
“A person who participates in an arrangement, agreement, practice or scheme under subsection 2 commits an offence and shall be liable, upon conviction, to a fine not exceeding P100,000 or to imprisonment for a term not exceeding five years, or to both.”
CBN is a blatant pyramid scheme. Please don't risk your money, effort and time. And your liberty.

And some more. Some screenshots of conversations with people marketing CBN in Botswana.


4. The broken tablet
“I bought my son a tablet for P399 and its still under warranty. After two weeks my son tells me the screen broke and I decided to check with the store for repairs. They called me after few days and explained that they can help me provided I pay P300 for screen, I then told her that am not happy because the price is worth buying a new one. I am not impressed at all with this because I even pleaded with manager to say they can’t charge me almost the same amount as new tablet and I even offered to at list pay P200.”
Section 13 (1) (a) of the Consumer Protection Regulations requires suppliers to offer commodities and services that are "of merchantable quality". It doesn't say they must prevent you or your children from breaking things.

In this case the store hasn't done anything wrong. Your child broke the device and it's your responsibility to either pay for it to be fixed or to buy a new one.

Friday, 14 December 2018

Radio show notes - week beginning 3rd December 2018

Source: Wikipedia
1. Who owns the car?
“I bought a Mercedes Benz on the 8th of October from a garage in Mogoditshane. After I paid they pretended that the blue book was not in the office and the sales man who assisted me said he was going to fetch it at his house. I waited till it was dark but ended up going home. Until now I don't have the papers for the car only the receipt. Please how do I get help on this matter?”
Who actually owns this car? Did the dealer ever have the blue book? Did he ever actually  own the vehicle that he sold? Is it possible that the previous owner is still the registered owner? Without the blue book, nothing can be certain.

My suggestion? Cancel the deal in writing. Quote S15 (1) (e) of the Consumer Protection Regulations which says that when a deal is properly cancelled the seller must “promptly restore” any money paid up front. Then contact Consumer Protection Unit and complain to them. Then call the Police and mentioned Section 308 of the Penal Code (“Obtaining by false pretence”) and then Section 310 (“Cheating”). See if that has any effect.

2. CBN - a pyramid scheme
(See also our press release about CBN here.)

“P100 can change your financial situation. CBN is a way to go. Join me today and let me take you through the journey of that financial change. You won't regret taking that decision. Drop your number now. Remember your P100 is a once off.”
Apparently you can join for just R100 and recruit 6 people, “You earn R10 per downline” and then get P60. And then so on, through several levels:
  • Level 1 Worker
  • Level 2 Supervisor
  • Level 3 Manager
  • Level 4 General Manager (at which you apparently get a laptop worth R4,000, groceries R2,000 and a Marketing allowance of R500.)
  • Level 5 Assistant Director (at which you get a Sun City holiday)
  • Level 6 Director (now you get a car worth R200,000)
  • Level 7 Acting CEO (another car, this time worth R500k)
  • Level 8 CEO (yet another car, now worth R1,200,000, a house valued at R2,500,000 along with furniture worth R500,000). 


CBN claim that:


“It’s simple to work with us: Recruitment only, no selling products, no products maintaining.”
Section 9 of the 2018 Consumer Protection Act defines a pyramid scheme as a scheme:
“where participants in the scheme receive compensation derived primarily from their respective recruitment of other persons as participants”
It goes on to warn that:
“A person shall not directly or indirectly promote, or knowingly join, enter or participate, or cause any other person to promote, join, enter or participate in… A pyramid scheme”
and that:
“A person who participates in an arrangement, agreement, practice or scheme under subsection 2 commits an offence and shall be liable, upon conviction, to a fine not exceeding P100,000 or to imprisonment for a term not exceeding five years, or to both.”
CBN is a blatant pyramid scheme. Please don't risk your money, effort and time. And your liberty.

And some more. Some screenshots of conversations with people marketing CBN in Botswana.


3. Déjà vu?
“My 72 year old mother went to a general dealer to buy groceries, while at the shop she tripped and fell. When she fell she had a bottle of tomato sauce in her hand which broke and severely cut her between the thumb and the second finger injuring 2 arteries. She almost bled to death. I called the owner of the shop who said will come and check us. My mother had 24 stitches to close the wound, was admitted for 4 hrs, now discharged. Other customers said this happened before. What are her rights?”
This is like deja vu all over again. Consumer Watchdog first big issue was very similar to this. Fifteen years ago we heard a similar story of a customer injured in a store. The store failed to respond adequately, we reported this, then received a threat of legal action (which we laughed at), kept pestering them and eventually, after they conceded they had lost significant levels of business because of their poor response and the public backlash, they settled.

It's very simple. It's the responsibility of store, restaurant, hotel, bank, insurance company, radio station, whoever, the protect the safety o their customers.

So maybe the store has a public liability insurance policy and they can claim against that? If yes, the matter is simple. If not, they need to start saving for the penalty a court will impose. Maybe they should settle before it gets to that stage?

We contacted various major store chains (not connected to this incident) to get their reactions. They all told us that they have public liability insurance policies. If an incident happens, they fill in forms, the customer provides medical documents, makes an official statement, a claim is submitted and a payment is made.

BUT it seems that public liability insurances NOT mandatory. This needs to change. Will contact MITI and urge them to intervene. Some might argue it'll be too expensive but I suspect not as expensive as not having it. How much will it cost if a customer is seriously injured, maybe even dies?A lot more than a small monthly premium.

4. Is this defamation?
“My brother and my mother went to a store to buy some few groceries. My brother then wrote his phone numbers to enter a competition that is running in their stores. After leaving the store he was called back that he won some groceries and as he was home with the baby cousin, he went with him to the store.

Upon arrival he was thrown into the office after people threw insults at him that he is a thief. He later learned that there was a man who went back to the store and accused him of stealing his wallet. He was not allowed to do anything or attend to the baby cousin, and he was promised a good beating because he stole. He managed to call me during that of which I asked my husband to rush there. When he arrived he found him still in a good state and with the police already there. After looking at the store cameras he was cleared that he did not steal the wallet as he did not even come close to the man who reported him.

Ever since then my brother is stressed and we would like to know which steps he can take for them to pay him back for defamation of character or something along those lines because I strongly believe the store manager should have checked out the store cameras before even calling him.”
Let's remind ourselves of the case of Molefe vs Scorpion Security in 2013. A lady had her bags searched by a security guard as she left a supermarket without her consent. The humiliation of being accosted in public and being accused of being a criminal angered her so much that she took the security company to court.

And she won.

In his ruling, the judge said:
“I find that indeed the Defendants searched the Plantiff without her consent and it was unlawful. On the issue of damages, considering the humiliation embarrassment and impairment of her dignity as an honest member of society I have considered that P60,000 would be sufficient for her dented image in society.”
Those of us who are not criminals have a right to our "dignity as an honest member of society". If this store wants to avoid a ruling against them, they need to start calculating how much they should pay the guy to keep this out of court.

Sunday, 11 November 2018

Radio show notes - week beginning 5th November 2018

Source: Wikipedia
1. Should they compensate me?
“I bought some food in a store which I later found to have gone bad after a bite or two. I took the item back and was told by the store that indeed it had gone bad. They replaced it with on OK one and said because they didn't make me pay for it, they had compensated me. I did not feel satisfied considering that I had first been thrown from pillar to post before seeing the manager who also said the same thing. Also my time spent in going back to the store. I just wanted to ask from you, is there compensation that I should have received in that situation or an apology is as far as it can get?
Various laws and regulations apply here. The Food Control Regulations, Public Health Regulations and the Consumer Protection Regulations, in particular Section 13 (1) (a) which requires a supplier to offers commodities and service that are of “merchantable quality”. Clearly this food was not that.

The general rule is that when something is wrong with an item you're entitled to one of the three Rs: a refund, repair or replacement. In this case you got a replacement so in theory they've done all they need to do. However, this is actually more serious. This is a food safety issue. People die because of poor food hygiene. I think you deserve slightly more than just a replacement. I think you deserve a sincere apology, an explanation of what went wrong and some assurance that it won't happen again. I don't think that's too much to ask.

2. Where are the photos?
“We paid a local photography company for wedding coverage last year around June-July. The wedding was held in October and its been over year now still waiting for our package. We paid them about P13,400. We have followed up and followed up to this day but they are tossing us from pillar to pillar, story after story, they are not taking our calls anymore, they only respond once in a while through WhatsApp. We didn't sign any agreement with them because we had assigned a family friend who is a friend to the photographers to handle the photography part but we have proof of payment. We used bank transfer to pay them the total charge once off. The family friend has tried to intervene but to no avail. Kindly advise.”
What is it with the wedding industry. Why do they have so many crooks and incompetents?

The good news is that when we contacted this photographer he responded with: “I’m working on their package, supposed to be done by the end of the coming week.”

And he did.

3. Ponzi Scheme Alert: Amazon Web Coin

A member of our Facebook group got in touch to report that he received a message saying:
“Am called Dr Ronnie Gitta from Uganda. Am coming to your country”
He told us that:
“a day after introductions, he even wanted me to already be bringing other people his way and I don't even know anything about his product/ service. Very shady indeed.”
Here are some quotes from their web site:
“Get maximum benefits from cryptocurrency investments”.
“Daily profit accruals range from 3% to 8% depending on the investment package chosen.”
“Basic trader” “$20-$500” “8% daily for 20 days. 160% total return”
“Elite trader” “$20,000-$50,000” “3% daily for 100 days” “300% total return”
“Referral program - tell your friends, relatives or colleagues about the company. If your information is appealing to them, and they become our investors, you will be paid a referral commission! You can go further to build your own team, attracting new investors because we have made a special four-level program of affiliate rewards.”
This is a Ponzi scheme. All the usual clues are there. They promise miraculous interest rates with no indication of how they can be achieved. There is no explanation of where the growth in money comes from. It's all unbelievable. There are also some obvious clues, including this:
“Your deposit runs forever and you will never get it back.”
There are other clues. Their domain was only registered on 27th September this year. Although they claim that “Amazon Web Coin was officially incorporated in August 2016 under registration number 10351681” in the United Kingdom they also say that they're registered in Hong Kong. I checked and the UK companies register says the company was “Dissolved on 30 January 2018”.

Amazon Web Coin is a Ponzi scheme and everyone is warned to avoid it!

4. Managing debts. Or not managing them.
“I want to know how this thing of sending names of debtors to ICT works. I’m owing a cash loan and they sent my name to ICT. Now they are starting to take legal actions on me. The problem is that they have blocked me so I can’t have even a short loan to clear them. Is it not double punishment? Is that how it has to be?”
Yes, that's exactly how it works.

Firstly, creditors (the people we owe money) are entitled to send debt collectors and attorneys after us to collect their money. Wouldn’t you do the same if the situation was reversed?

Secondly, creditors are entitled to register our debts with credit reference bureaux. Their databases hold full financial records, both good and bad. These records allow other lenders to make sensible judgments about whether they should lend us money based on our previous history.

In this vase the customer has a history of defaulting. Why would another lender trust him?

We've put him in touch with a debt counsellor who should be able to help him sort out his finances.

5. Plastic bags. Again.

Are they banned? They were meant to be banned on 1st November but the Powers-That-Be changed their minds. So they're not banned yet. BUT they will be, sooner or later.

And the other issues. The so-called “Plastic bag levy”? Did it ever exist?

No.

What happened was that a compulsory standard for plastic bags ("FDS 186:2016, Plastic carrier bags and flat bags — Specification") was introduced but the Botswana Bureau of Standards. This meant that stores were then mean to offer us higher-quality plastic carrier bags that cost the stores more money. They just passed the cost on to you an me.

But be warned. Plastic bags will be banned along with plastic bottles and straws, sooner or later. Get ready now.

Friday, 3 August 2018

The Voice - Consumer's Voice

Why have they blacklisted me?

I need your help with my old bank. I had a credit card with them that I owed P2,080 that I had paid fully in November 2017. I was shocked yesterday when I went to my new bank to get a loan to be told I have been listed at CRB by the old bank on 24 January 2018. I went to the bank livid and I was told they don’t know what really happened and they wrote a letter for me to take to my new bank to assure them that they erroneously listed me at CRB. Théy promised to solve my issue first thing tomorrow morning. I couldn’t sleep last night wondering what the implication of being listed at CRB means for my credit rating because of someone else’s carelessness in their job. I want to know the implications even if they promised to remove me on Monday morning?


Let’s start by explaining how credit reference bureaus operate. They don’t “blacklist” people, unlike what most people will say. In fact, they record everything, both good and bad. They record when we get a loan or buy something on hire purchase, they record when we repay these commitments properly and also when we fail to do so. The recent financial history they hold on us is then used by lenders to help them decide whether to lend more money to us. There’s nothing wrong with this because it helps them to take the right decisions. It helps them to lend money to the people most likely to repay it and to avoid lending to people with a recent history of not meeting their obligations.

However, mistakes are obviously sometimes made. From what you say, it seems like your old bank clearly made a serious mistake when they recorded that you still owed them money. If it’s true it’s the responsibility of the bank to fix this problem by correcting your record so that this alleged debt completely disappears and that their mistake doesn’t disadvantage you in any way.

We’ll also get in touch with them to encourage them to move more quickly!

Should I attend the presentation?

I received an invitation from someone in Tanzania to attend a presentation in Gaborone and training on something called Magellan International run by a company called CGi Limited. Do you think this is genuine?


I think it’s a genuine scam.

CGI Limited now call themselves CGI Global and on their web site they suggest that they have interests in “Mobile Technology”, “Online Shopping” and, guess what, “Cryptocurrency Mining”. They even claim to have their own cryptocurrency that they call Betchip. They say that this is “a new digital coin to the market” and that it “can be used within the CGi economy in selected stores and services online.” They go on to suggest that recruits can buy them at “$1 per coin* and that there will be “a huge profitable opportunity when the coin will go as high as $10,000 or more” and that “all you need to make the profit out of Betchips is to invest now while stock last.”

However, there’s no evidence that any of this is actually true. There’s no evidence that this “Betchip” currency really exists and it’s certainly bizarre to think that a currency that doesn’t even exist can increase in value by up to 10,000 times. Yet again, this is a scam is exploiting public ignorance about cryptocurrencies like Bitcoin.

Even though their web site is registered in the USA earlier this year, it’s strange that their web site says that their services are “not available in certain countries and territories including United States of America”. Also, almost all of the advertising seems to be focussed on Africa. This obviously conflicts with a post on their Facebook page which suggests that 52% of their visitors are from the USA and that “These are now seeing what we don't see!!!” Many things don’t add up.

The facts are quite simple. Any scheme that claims it can convert a $1 investment into $10,000 is a scam, almost certainly a Ponzi scheme. Any scheme that claims you can make fortunes from “investing” in a cryptocurrency is certainly a deception. Please don’t waste your time, effort and money on what is clearly a scam.

Friday, 13 July 2018

The Voice - Consumer's Voice

Should I join Bitcoin?

Hello Sir I am interested in joining Bitcoin but I need someone who can explain so I understand better. There is this other gal who tried to explain but I really don’t understand her. May you kindly be of help, especially mining the bitcoins.

Bitcoin is a currency, like the Pula, the Rand, the US Dollar and Euro but unlike these conventional currencies, Bitcoin is a “cryptocurrency”. Cryptocurrencies aren’t currencies that you can carry in your pocket, purse or wallet. There are no coins or notes, they exist in cyberspace.

That’s one reason why Bitcoin should never be seen as an investment. Currencies aren’t investments, they’re things we use to trade with, to buy and sell things and the people who trade between currencies are speculators, not investors. They’re more like gamblers.

Data source: Coindesk
Another reason why Bitcoin shouldn’t be seen as an investment is that like all cryptocurrencies, they’re enormously volatile and unpredictable. Their values can go up and down remarkably quickly, much more than real investments and conventional currencies. Bitcoin advocates will often tell you that Bitcoin’s value increased enormously in 2017 and that’s true but what they often fail to explain is that its value then dropped by two thirds. Anyone who “invested” in December last year would have since lost two thirds of their money today.

Consumers should also know that unlike conventional currencies, there are no protections, no safeguards, no regulators overseeing Bitcoin. There’s nobody to turn to if something goes wrong. Nobody at all.

You asked about Bitcoin mining and that’s a complicated issue. Every time someone buys, sells or transfers using Bitcoin, that transaction has to be verified by computers around the world that hold the “blockchain”, the "distributed ledger" of all transactions. That’s basically what Bitcoin mining is and the people running those computers can earn Bitcoins themselves as a result. However, the computing power needed to do this is enormous and huge “server farms” are required to do it. It’s something way beyond you or me.

Perhaps the greatest danger is that Bitcoin and other cryptocurrencies are surrounded by a huge range of scams, pyramid schemes and Ponzi schemes.


Ask anyone who encourages you to join a scheme, how does it benefit them? You’ll soon see that it’s all about recruitment and nothing to do with Bitcoin.

Should I inform them?

I want to ask what happens when all along I have been paying an instalment at furnisher shop, and all of a sudden my contract is terminated and I struggle to pay. It was an instalment of about 14k, and during the period I was working I really pushed to reach half of the sum. Am now owing 7k, and unfortunately our contracts ended.

Should I go to the furnisher shop with letters showing them am still unemployed so that they stop putting more interest in my debt? Am willing to settle the remaining balance, but am still called by finance people reminding me to come pay though am not working. What should I do?

Unfortunately I don’t think I can give you any good news. Very often hire purchase agreements include an insurance policy that covers you for unexpected retrenchment but that’s not what happened to you. From what you say, it seems like you came to the end of your contract and I guess that was something you knew was going to happen? Even if you didn’t know in advance, you presumably knew that your contract could have been terminated like this? Personally, I think that the store should have checked this before they accepted your business. They should have asked you to prove your employment was permanent and not fixed-term or liable to be terminated like this. Before you enter into any financial arrangement you need to be 100% certain that you’ll be able to pay for it all. You need to know that you’ll have income to support the payments you’ll need to make.

What you absolutely must do is exactly what you suggested. Go to the store and explain to them that you are now unemployed and that you’re going to have some difficulties making the remaining instalments. See if you can agree a repayment plan that you can stick to. With luck they’ll be helpful.

Friday, 30 March 2018

The Voice - Consumer's Voice

What is Carcoin?

Could you kindly investigate and give me your thoughts on Carcoin? I have been invited to some presentations at the Avani hotel and it seems this "investment scheme/cryptocurrency" is picking up pace in Botswana. I did some research of my own and it seems one first has to invest $200. What are your thoughts?

My thoughts are very simple. I think it's a scam. And I'm not wrong.

They describe themselves as a "car sharing community" and say that there is "no need to buy any car" and that they "are always there at your service". They then go on to explain that they are basically a taxi firm that "is available in every city we operate in". But they don't say which cities that might be, so I think it's safe to say that this isn't true. They even claim to be developing an app that you can use to call for a ride but this isn't going to available, they say, until December 2019. So far so suspicious. Clearly they are pretending to be something like Uber, the taxi company that operates in various cities around the world, even as close as Joburg. I've used Uber there and it's a truly remarkable way to get around. But Carcoin isn't Uber.

Soon things become a lot clearer. They start hinting that they are using blockchain technologies, the same technology used by Bitcoin. There's nothing inherently suspicious about that, the blockchain concept is certainly going to play a role in business in the future but there's no evidence this is true in the case of Carcoin. They also suggest that you can buy Carcoins, suggesting that they have their own cryptocurrency like Bitcoin. Again, there is no evidence to believe this.

I think I know what's going on here. Carcoin are exploiting the ideas behind Bitcoin and Uber to get our money from us. The clue is on their web site when they say that if you want to buy Carcoins you can do so using Bitcoin. So you give them your genuine Bitcoin cryptocurrency and they give you their fake Carcoins in return. All you'll be doing is giving your money away and getting nothing in return.

Finally, the so-called CEO of Carcoin has a history of connection with dodgy schemes so I think it's reasonable to assume that Carcoin is no more than a Ponzi scheme. Simple as that.

What is Randbuilders?

I was invited to join Randbuilders recently. Do you know about it?


You're not the first person to ask that recently. Randbuilders seem to have decided to bring their money-making scheme from South Africa to Botswana! Aren't we lucky?

Actually we're not. They describe themselves as "a Multi Level Marketing Business which enables Participants to learn to master the business of network marketing while creating an additional income stream for themselves" but they're nothing more than a pyramid scheme. The difference between a Multi Level Marketing scheme and a pyramid scheme is the former has products to sell. If you think of MLMs like Amway and Herbalife, while you won't make any money from joining their pyramid-structured business, at least there are some products to buy. With a pyramid scheme there are no products and Randbuilders is a very good example of that.

The only reference to products I could find on their web site said that when you join the scheme "you purchase master resale right to promote your own business". That's just silly. You pay to join their scheme and then you get the right to advertise your own business? Something you can do for free anyway?

The only thing that Randbuilders wants is multiple levels of recruitment and the flow of money up the pyramid they're trying to build. And they need victims to do that. Do you really want to be one of their victims?

Guess what else I discovered about Randbuilders? The person who registered Randbuilder's domain name in December last year was also an active recruiter for MMM Global, the collapsed Russian Ponzi scheme and is connected to a wide range of other schemes. Yes, you CAN judge someone by their history of involvement in scams!

Monday, 19 February 2018

Vortex Profits - Central Bank of Ireland warning

The Central Bank of Ireland has issued a warning about Vortex Profits.
"The Central Bank of Ireland (‘Central Bank’) today (19 February 2018) published the name of an unauthorised firm, Vortex Profits Limited (Ireland). Vortex Profits Limited (Ireland) is not authorised by the Central Bank as an investment firm, investment business firm or to provide investment advice."
Many thanks goes to our good friend James Fern from the SCI Group who alerted the Central Bank of Ireland to the issue.

Background

The people promoting Vortex Profits claim that the company is “a remarkable investment platform … with an outstanding track record of 2 years for delivering best of class investment solutions and endless income-generating opportunity”. They suggest that investors can earn returns of between 2.5% and 4% every day by investing through Vortex Profits in Bitcoin, gold or oil.

These suggested earnings are clearly impossible, given that 2.5% per day implies an annual equivalent of over 800,000%. Even more unbelievably, a 4% return per day equates to an annual return of over 158,000,000%.

The facts are that the company was only registered in the Republic of Ireland in September 2017, contradicting their claim of a “track record of 2 years”. Furthermore, the physical address they offer is an accommodation address shared by hundreds of other companies and the telephone number they offer is not even in the Republic of Ireland but is in Sweden.

They claim to have been founded by someone called Griffin Wrights who they describe as a "renowned Entrepreneur" with "countless years of experience being a financial Planner". However, no trace exists of this person before or outside of Vortex Profits.

Given the contradictions and the ridiculous claims about the profits that can be made by “investing” in their schemes Consumer Watchdog suspects that Vortex Profits is nothing more than a Ponzi scheme and we urge consumers to exercise extreme caution when engaging with them.

Saturday, 17 February 2018

Radio show notes - week beginning 12th February 2018

Source: Wikipedia
1. When a company goes bust

Two very similar emails arrived on the same day.
"I made a laybye purchase in a shop that was operating in Game City. Yesterday I went to the shop wanting to pay the remaining balance so that I could collect the bed I had purchased. Unfortunately I found the shop closed and locked with no sign of operation. I called one of the employees and he told me that the shop had been closed indefinitely and could not provide further details. I have paid P4,500 towards my purchase."
"I purchased a couch from a store in Game City in December 2017 and till this date they have not delivered the couch to me. They keep telling me that the owner of the store has fled the country so they have closed up all his shops as well as his warehouse therefore they can't deliver the couch. This is so unfair to me as I have fully paid for the couch so please assist me on a way forward regarding this matter."
Both related to the same store at Game City. So what can these customers do? If the company has no assets left there'll be nothing to seize, nothing to claim against. Probably best to instruct attorneys and see what they can do.

2. Whose car was it?
"I sold my car. The next day he called me and says my car is overheating. He demands his money back and he says I should take my car back, I told him thats not possible because I have already spend the money. We did not make a written agreement it was verbal. He then called me again complaining that the signatures on the blue book are not the same with the ones on my id copy so they declined to help him change names at transport. The signature is from the previous owner not me. I never changed it when I bought it from the previous owner and never made a written agreement with the guy before. I would really appreciate a way forward to this because this guy is really bothering me."
Who actually owned the car? There was no sale agreement when this guy bought the vehicle and the vehicle registration documents were never updated to show him as the owner. So did he actually own it? Is it possible that it's still owned by the previous owner? If so, was he entitled to sell it? Given that there's no proof of sale, and no updated blue book, who knows?

The danger is that the new "owner", the guy that doesn't want it any longer could get the current "owner" into a lot of trouble. Maybe he could even argue "Obtaining by false pretence"?
It's time to refund the latest buyer and take the car back.

3. Vortex Profits (again)

Vortex Profits claim that they are "an absolutely new revolutionary concept, a remarkable investment platform of a new era with an outstanding track record of 2 years for delivering best of class investment solutions and endless income-generating opportunity".

They say that you can join by paying between $25 and $50,000 (around P250 to P500,000) and that you can then earn returns between 2.5% and 4% return per day. Remember you'll be lucky to get a bank to offer more than 2.5% per year. In fact, if this was true (and it's obviously not) and you "invested" P1,000 today at 2.5% per day, after a year you'd have over P12 million. At 4% per day, you'd have over P3 billion. This is clearly nonsense. Only Ponzi schemes makes these claims.

There are some other clues that this is a scam. Their domain was registered in August 2017 and the company was registered in the Republic of Ireland only in September last year. The physical address the give in Dublin is just an accommodation address shared with many other "companies". The supposed founder of the company, someone they call Griffin Wright, and who they say is a "renowned Entrepreneur" and who has "countless years of experience being a financial Planner" doesn't appear to actually exist. There's no trace of him existing outside this bogus company.

Vortex Profits is a Ponzi scheme. Remember Eurextrade? Its twin brother has arrived.

Saturday, 20 January 2018

The Voice - Consumer's Voice

This week The Voice published our press release regarding the Vortex Profits Ponzi scheme.


Consumer Alert: Vortex Profits

Consumer Watchdog would like to alert consumers about Vortex Profits, an apparent Ponzi scheme currently trying to recruit victims in Botswana.

The people promoting Vortex Profits claim that the company is “a remarkable investment platform … with an outstanding track record of 2 years for delivering best of class investment solutions and endless income-generating opportunity”. They suggest that investors can earn returns of between 2.5% and 4% every day by investing through Vortex Profits in Bitcoin, gold or oil.

These suggested earnings are clearly impossible, given that 2.5% per day implies an annual equivalent of over 800,000%. Even more unbelievably, a 4% return per day equates to an annual return of over 158,000,000%.


The facts are that the company was only registered in the Republic of Ireland in September 2017, contradicting their claim of a “track record of 2 years”. Furthermore, the physical address they offer is an accommodation address shared by hundreds of other companies and the telephone number they offer is not even in the Republic of Ireland but is in Sweden.

They claim to have been founded by someone called Griffin Wrights who they describe as a "renowned Entrepreneur" with "countless years of experience being a financial Planner". However, no trace exists of this person before or outside of Vortex Profits.

Given the contradictions and the ridiculous claims about the profits that can be made by “investing” in their schemes Consumer Watchdog suspects that Vortex Profits is nothing more than a Ponzi scheme and we urge consumers to exercise extreme caution when engaging with them.

If consumers are in any doubt they should contact Consumer Watchdog for free advice. We can be reached by phone on 3904582, by email at watchdog@bes.bw or by joining our Facebook group, Consumer Watchdog Botswana.

Monday, 15 January 2018

Press Release - Vortex Profits

PRESS RELEASE
FOR IMMEDIATE RELEASE

15th January 2018

Consumer Alert: Vortex Profits

Consumer Watchdog would like to alert consumers about Vortex Profits, an apparent Ponzi scheme currently trying to recruit victims in Botswana.

The people promoting Vortex Profits claim that the company is “a remarkable investment platform … with an outstanding track record of 2 years for delivering best of class investment solutions and endless income-generating opportunity”. They suggest that investors can earn returns of between 2.5% and 4% every day by investing through Vortex Profits in Bitcoin, gold or oil.

These suggested earnings are clearly impossible, given that 2.5% per day implies an annual equivalent of over 800,000%. Even more unbelievably, a 4% return per day equates to an annual return of over 158,000,000%.

The facts are that the company was only registered in the Republic of Ireland in September 2017, contradicting their claim of a “track record of 2 years”. Furthermore, the physical address they offer is an accommodation address shared by hundreds of other companies and the telephone number they offer is not even in the Republic of Ireland but is in Sweden.

They claim to have been founded by someone called Griffin Wrights who they describe as a "renowned Entrepreneur" with "countless years of experience being a financial Planner". However, no trace exists of this person before or outside of Vortex Profits.

Given the contradictions and the ridiculous claims about the profits that can be made by “investing” in their schemes Consumer Watchdog suspects that Vortex Profits is nothing more than a Ponzi scheme and we urge consumers to exercise extreme caution when engaging with them.

If consumers are in any doubt they should contact Consumer Watchdog for free advice. We can be reached by phone on 3904582, by email at watchdog@bes.bw or by joining our Facebook group, Consumer Watchdog Botswana.